Your money habits have a history. You can change what comes next.
Nobody sat you down and taught you how to think about money. You absorbed it — from overheard arguments, from the friend whose car was newer than yours, from whatever your parents did or didn't say at the dinner table. That secondhand education is still running in the background of every financial decision you make today. Here's how to actually find it, and change it.
- Where your money mindset actually came from
- Do you actually know what yours is?
- Why so many people struggle with money
- The behaviors worth catching in yourself
- How to actually shift it
- Building an abundant mindset, one habit at a time
- Turning the mindset into actual money moves
- Where this actually leaves you
Where your money mindset actually came from
As a kid, you didn't get a lesson on money. You got exposure — overheard arguments, offhand comments, the friend who showed up in a brand-new car versus the one in hand-me-downs. You weren't in a position to judge whether any of it was true or useful. It was just normal, so it stuck.
If money was talked about openly in your house growing up, you probably have a reasonably healthy relationship with it now. If it was a source of conflict, or never discussed at all, there's a decent chance your relationship with money is more complicated than it needs to be — even if your bank balance looks fine on paper. Plenty of people who are objectively doing well still feel uneasy about their own money, because the discomfort was never really about the numbers.
A useful place to start is noticing the habits you bring to everyday decisions. When a month feels tight, look at both the numbers and your routines: bill timing, irregular costs, and spending habits can all play a part. A shortfall is not proof of a bad attitude or a lack of discipline.
Do you actually know what yours is?
Most people have never sat down and actually named their own money mindset. Try answering these honestly — not how you wish you'd answer, how you actually would.
Ask yourself
- Does money cause you uneasiness, even when things are fine?
- Did you consider yourself rich or poor growing up — and was that even accurate?
- Was money a source of conflict in your house?
- What's your actual earliest memory involving money?
- Can you talk about money out loud, comfortably, with another person?
- Do you see yourself as successful, or as struggling — regardless of what the numbers say?
- How much mental space does money take up on an average day?
If your honest answers come with anxiety or a tight chest, that's information — it usually means the mindset needs work more than the budget does. If they come with something closer to ease, you're probably in better shape than you give yourself credit for.
You are, for the record, the only person in charge of what happens next with any of this. Not your parents, not the friend with the nicer car, not whatever number is currently in your account. You decide whether it changes.
Why so many people struggle with money
Most people don't realize that how they think about money quietly sets the ceiling on how they live. If you believe you can't possibly live on less, or that you could never earn more, you've usually just made that true by believing it. A few specific mindsets do most of the damage:
- "I deserve this right now." The desire to have something today is almost always louder than the discipline to save for it — and most of us have never been taught to sit with that gap on purpose.
- "Budgeting is painful and complicated." A belief inherited from decades of genuinely tedious budgeting tools, not from budgeting actually being hard.
- Poor role models. If the adults around you were bad with money, you likely absorbed some of it as normal — the same way you'd absorb an accent.
- Not knowing where the money actually goes. The financial equivalent of putting your head in the sand — and the single most common reason people feel behind without being able to say exactly why.
- Keeping up with everyone else. A large share of working adults have little to no retirement savings, in part because "living in the moment" quietly became "spending like the people I follow online."
- Genuine bad luck. Not everyone struggling has bad habits — medical bills alone wipe out savings for plenty of financially disciplined people. This one isn't a mindset problem, and it's worth not shaming yourself over it.
Every one of these is a learned habit, which is the good news hiding inside the bad news — habits can be unlearned.
The behaviors worth catching in yourself
Bad money behavior is hard to catch in real time, because it doesn't feel like a decision — it feels like an impulse. A few specific patterns to watch for:
- "I have to have it now." Next time you're eyeing something new, sit with it for a few days first. Ask how many hours of work actually paid for it.
- The paycheck-to-paycheck treadmill. Usually caused by being quietly overextended, not by earning too little. The fix starts with trimming, not earning more.
- Upgrading your life every time your income goes up. If a raise always turns into a bigger loan payment, you never actually get ahead — you just get a nicer version of the same treadmill.
- Never taking a financial risk. Fear of any risk quietly caps how far your money can go. Small, considered risks build the confidence that bigger decisions later require.
- The scarcity/either-or trap. The belief that there's only so much to go around, so you'd better grab it now. It's rarely true, and it makes decisions worse, not safer.
- Refusing to learn anything new. Not knowing your own credit score, or where your money actually goes month to month, isn't neutral — it's a decision with consequences.
- Missing the bigger picture. A big paycheck isn't wealth. Net worth is wealth. Spending everything you earn keeps the two permanently unrelated.
- Being your own worst advocate. If you don't push back on bad deals, predatory lenders and pushy salespeople will happily make decisions for you.
These are just habits, built over a long time — which means changing them is a daily practice, not a single decision you make once and never revisit.
How to actually shift it
Changing your mind about money can feel genuinely impossible, mostly because most advice skips straight to "just think positive." It doesn't work like that. It works more like this:
- Notice the thought. Catch the actual money challenge you're facing and look at it plainly, without immediately trying to fix it. Feeling bad about it here is fine — it's often what motivates the rest.
- Let yourself feel it. Guilt, shame, anger, envy — whatever shows up, let it be there instead of pushing it down. Naming the feeling is what makes it possible to think about clearly.
- Let the change actually land. Once the emotion isn't running the show anymore, you can step back and see the actual behavior underneath it.
- Do something concrete. Set up a real budget, open an account, take a class, ask a genuine question. The mindset shift completes when it turns into an action, not a feeling.
Build your monthly plan through conversation
Budget Plan Agent helps organize your income, bills, spending, savings goals, and irregular costs into a monthly plan, a weekly spending number, and a 30-day action plan. It works with supported versions of ChatGPT and Claude; platform access is separate. It is educational budgeting support, not a replacement for professional advice.
List price $39 $17 one-time.
Building an abundant mindset, one habit at a time
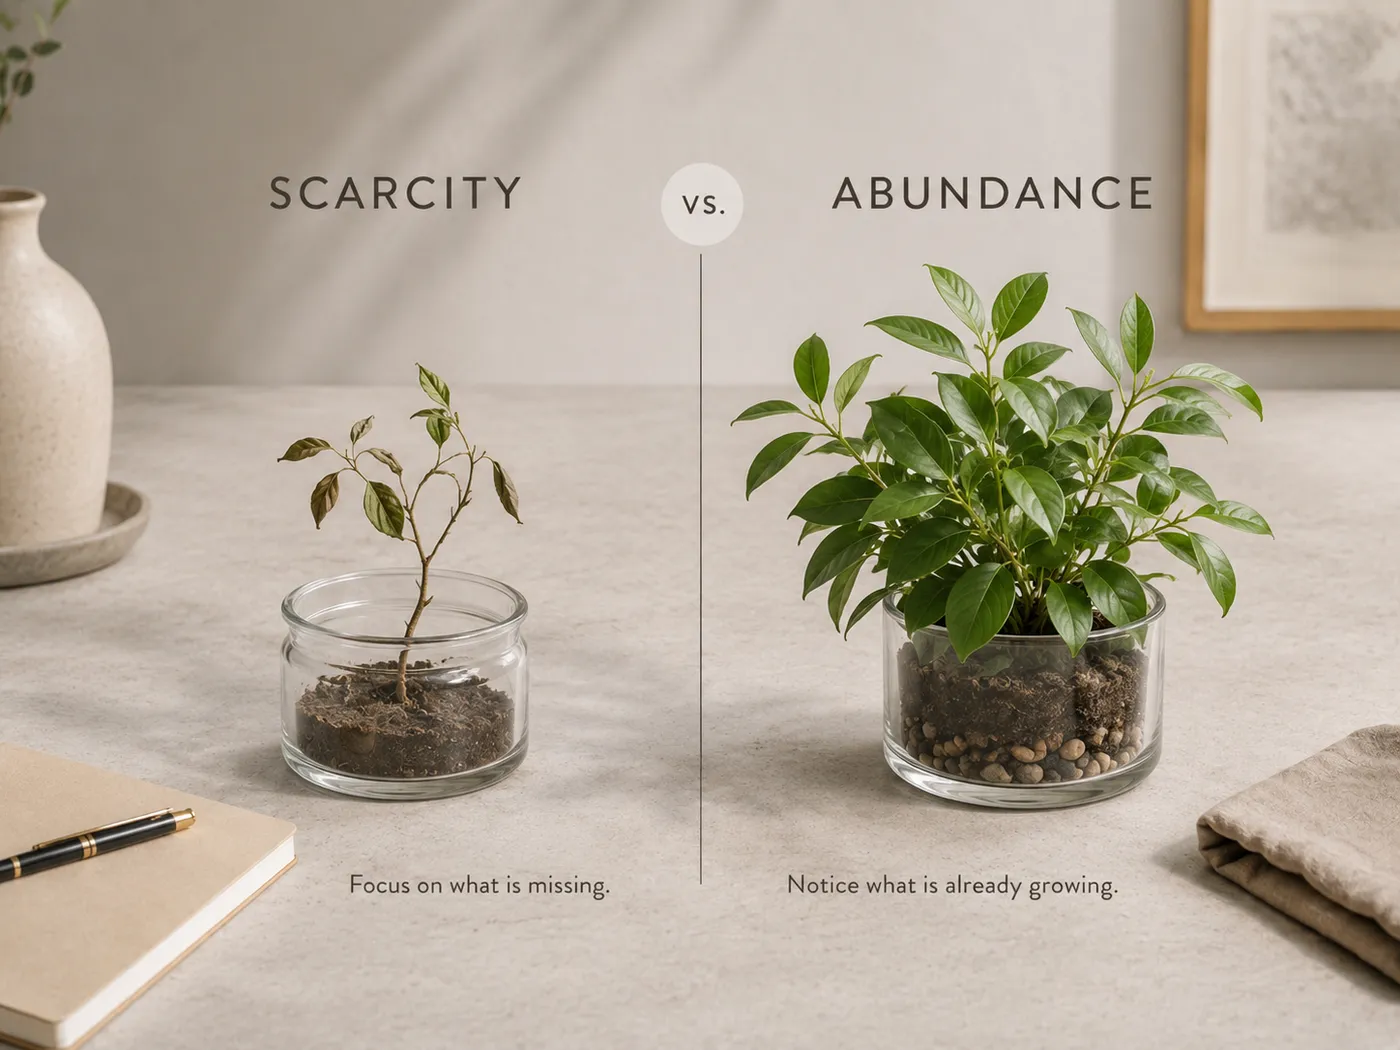
The opposite of a scarcity mindset isn't recklessness — it's a genuine sense that there's enough, and that your actions can create more of it. A few small practices that actually move the needle:
- Appreciate what's already yours — your health, your people, your home, before you think about what's missing.
- Keep a short gratitude list — even three or four honest lines a night, not a whole journal entry.
- Use a mantra, out loud — something as plain as "there is enough," said until it stops feeling silly.
- Look for the upside in a loss — not to deny it hurt, but to stop scarcity from writing the whole story.
- Build your knowledge on purpose — books, videos, real conversations with people who are good with money.
- Share some of it — money, time, or things you no longer need. It tends to loosen the grip scarcity has on you.
- Get physically organized — your space, your time, your files. Clutter and financial anxiety usually travel together.
- Believe you're allowed to do well — swap "why me?" for "why not me, too?"
- Stop measuring against other people — especially on social media, where you're comparing your real life to someone's highlight reel.
- Retire the excuses — name the actual belief or habit underneath the excuse, and work on that instead.
Turning the mindset into actual money moves
A healthier mindset matters, but it has to eventually turn into behavior — spending, saving, budgeting, and investing that actually reflect it. Here's where that gets practical.
Spending
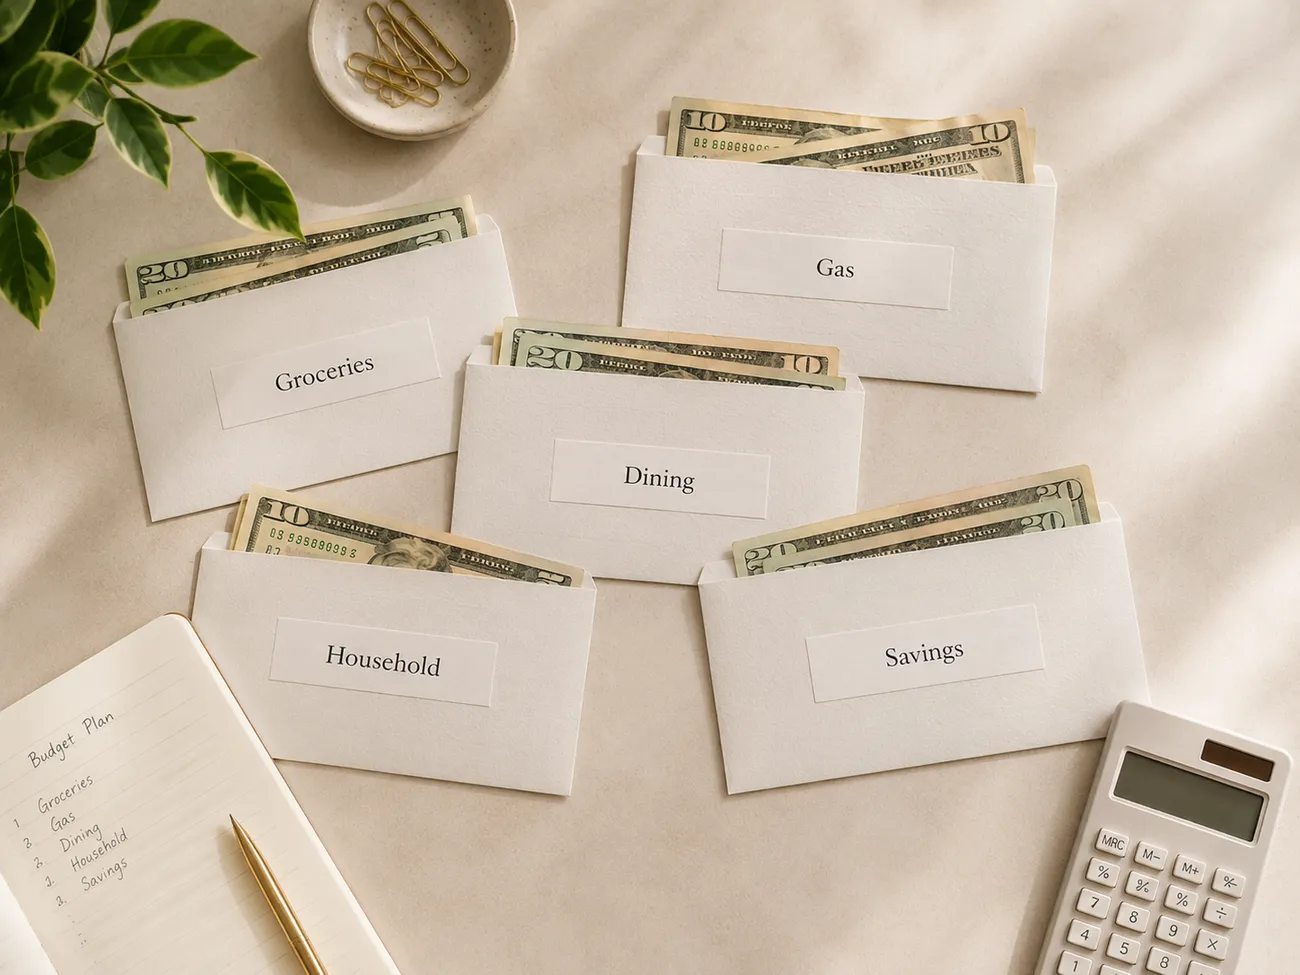
- Use cash for the categories that get away from you. Put physical cash in envelopes per category and spend only from what's there — it's the oldest hack in the book because it still works.
- Make impulse shopping harder on purpose. Delete bookmarked shopping sites, unsubscribe from catalogs, remove saved card details.
- Keep one credit card out, put the rest away. Not necessarily canceled — just out of easy reach.
- Plan meals before you shop, not while you're standing in the aisle deciding on the fly.
- Buy quality where it actually matters, instead of defaulting to cheapest — cheap that wears out fast usually costs more over time.
Give each part of your spending a place
TidyEnvelopes helps you organize spending and savings into digital envelopes. Record purchases, check recorded balances, and plan how to fund your envelopes on payday. You stay in charge of entering transactions and making any actual bank transfers.
List price $49 $27 one-time.
Saving
- Start an emergency fund first. It's what keeps a bad month from turning into a credit card balance or a payday loan.
- Make your goals feel real, not abstract. "Save more" motivates nobody. "$2,400 for a trip to Lisbon" does.
- Use an employer retirement match if one exists. It's one of the few genuinely easy wins in personal finance.
- Keep a separate fund for near-term wants. A vacation or a renovation, funded on purpose instead of financed after the fact.
Budgeting
- Track every dollar for 30 days first. You can't build a realistic budget on a guess about what you spend.
- Pay bills the moment they land, or put them on a calendar. Late fees are one of the few completely avoidable costs in personal finance.
- Categorize what you tracked. Food, shelter, savings, going-out — broken down enough to actually be useful, not so much that it's exhausting to maintain.
- Fund what makes you happiest, deliberately. If concerts matter more than daily coffee, let the budget say so on purpose instead of by accident.
A quick, honest correction
Older versions of this kind of advice point you toward Mint or Wesabe for automatic tracking. Wesabe shut down back in 2010. Mint was retired by Intuit in 2024, with users pushed toward Credit Karma. If you see either recommended anywhere, it's stale advice — worth knowing before you go looking for a login page that no longer exists.
Keep due dates, payments, and balances together
TidyExpenses brings recurring bills, partial payments, and remaining balances into one place. Review what needs attention, record what you paid, and see bills across the calendar. It tracks your entries; it does not make or verify bank payments.
List price $49 $27 one-time.
Bring your household budget into one view
TidyBudget brings budget tracking, bills, accounts, debt tools, and sinking funds into one browser-based app. Use household and personal views to organize your own numbers and keep future expenses in the plan.
List price $69 $47 one-time.
Investing
- Start once your savings has real footing, not before — investing is not where an emergency fund belongs.
- Get clear on your actual risk tolerance and timeline before picking anything, not after.
- Build low-risk first, then layer in more risk as the foundation gets sturdier, not the other way around.
- Diversify on purpose, across types of investments, not just across a handful of similar stocks.
- Decide how hands-on you actually want to be, and bring in a real advisor if the honest answer is "not very."
Investing decisions are genuinely personal and often tax- and jurisdiction-specific — this is general information, not a recommendation for your situation. See our Disclaimer for the full picture.
Where this actually leaves you
Your money mindset comes down to how you were taught, directly or by osmosis, to think about money. A healthier one means changing the habits and thoughts that have been quietly sabotaging you — not through willpower alone, but through noticing, then acting, on repeat.
People who seem to have a natural knack for money usually don't. They believed they deserved to do well, they learned to save on purpose, and they weren't afraid of a considered risk. A few things they tend to have in common:
- They think long-term — adding value first, trusting the return follows.
- They know what they've earned — without an entitled attitude about it.
- They believe they deserve to do well — and act accordingly, on purpose.
- They know the value before they spend — not just the price.
- They shop around — and buy things worth more than what they paid.
- They respect compounding — every dollar spent today is a dollar that can't grow.
- They optimize deliberately — taxes, fees, timing — not aggressively, just on purpose.
- They skip the excuses — they figure out what went wrong, then try again.
You're in charge of which of these becomes true for you. Not your childhood, not your parents' habits, not the mindset you inherited by accident — you, starting with whatever you noticed while reading this.
If you want a number to start from
Mindset work is easier with something concrete to look at. The free Money Leak Score takes about two minutes, asks a handful of plain questions, and shows you the one leak worth fixing first — no bank login, nothing saved, completely free.