Financial planning for everyday people, not just the rich ones.
Nobody hands you a financial plan at 18 and says "good luck." Most of us figure it out as we go — usually badly, usually late. This is the version we wish someone had handed us: five real steps, no jargon, and enough honesty to admit when a plan is about to fail before it does.
- What "financial planning" actually means
- Step 1: Decide what you're actually saving for
- Step 2: Get honest about where you stand
- Step 3: Add up what you own, then what you owe
- Step 4: Pick a budgeting method you'll actually use
- Step 5: Actually track it
- The tools everyone recommends
- When to actually hire someone
- Why most financial plans fail
- Where to actually start
What "financial planning" actually means
Financial planning sounds like something rich people do with a guy named Chip in a glass office. It isn't. It's this: figuring out where your money's coming from, where it's going, and what you actually want it to do for you — this year, and for the rest of your life. That's it. Everything else is detail.
For most people, a real financial plan comes down to five things: setting goals, being honest about where you currently stand, knowing what you own versus what you owe, picking a budgeting method, and actually checking in on it. Skip any one of those and the plan quietly falls apart — usually around month three.
The good news: none of these five steps require a finance degree. They require about an evening, a notebook or a spreadsheet, and a willingness to look at numbers you might currently be avoiding. Let's go through them one at a time.
Step 1: Decide what you're actually saving for
Your goals should cover both this year and the next thirty. That's not as intimidating as it sounds — it just means you're thinking about paying off a credit card and retirement in the same sitting, instead of only ever dealing with whatever's on fire this week.
If you don't write a goal down and attach a plan to it, it mostly doesn't happen. Not because you're undisciplined — because vague intentions lose every time to a Tuesday.
12 goals worth stealing
You don't need all twelve. Pick the three or four that actually apply to your life right now.
- A budget you'll actually keep — realistic enough to survive contact with a real month.
- A 6-month emergency fund — enough to cover the basics if income stops tomorrow.
- Out of consumer debt — credit cards and payday loans specifically, paid off fast.
- An actual retirement number — even a rough one beats "later."
- College savings, if it applies — scholarships are not a plan.
- A tax check-in — most people overpay without knowing it.
- More than one income stream — even a small second one changes the math.
- The right insurance, not extra insurance — covered, not over-covered.
- A house down payment fund — 20% gets you meaningfully better terms.
- A vacation fund — so it's paid for, not financed.
- A big-event fund — weddings and grad parties are predictable, budget like it.
- An estate plan — unpleasant to think about, worse to leave to your family to sort out.
You can work on more than one at once — once your consumer debt is gone, most of these can run in parallel. The honest first move is just looking at your actual situation and picking where to start.
Step 2: Get honest about where you actually stand
For a lot of people, this is the step that gets skipped — because writing it all down is uncomfortable. You might be more in debt than you thought, or your savings might be thinner than you'd like to admit. That discomfort is exactly why this step matters: you can't fix a number you haven't looked at.
Answer these as plainly as you can:
- What's your net worth? What you own, minus what you owe. It's fine if it's negative — that's just where you're starting from.
- What's your actual debt level? Separate the unsecured stuff (credit cards, payday loans) from the secured stuff (mortgage, car loan). The unsecured debt is the one to attack first.
- What retirement planning exists already? A workplace 401(k), an IRA, nothing yet — just know which one it is.
- What does your credit report actually say? Pull it at least once a year, from all three bureaus. It catches mistakes and identity theft before they become a real problem.
- What are you saving, and where? Cash, short-term, long-term, investments — list it all in one place.
- What insurance do you actually have? Life, health, home or renters, auto — know what's covered and what isn't.
- What income opportunities are you not using? A side skill, a freelance gig, an obvious raise you haven't asked for.
The only way through this step is total honesty — every dollar in, every dollar out, every shortfall named instead of quietly ignored. It's uncomfortable for about twenty minutes and useful for years.
Step 3: Add up what you own, then what you owe
This is Step 2's numbers, formalized. Your assets are cash, checking and savings balances, CDs, money-market accounts, property, and anything else you could turn into cash without much trouble. Your liabilities are everything you owe under a contract — mortgage, student loans, credit cards, auto loans, personal loans, taxes owed.
One useful nuance: if you're paying for something month-to-month with no contract — a gym membership, a streaming subscription — it's a monthly expense, not a liability. You can cancel it in one phone call, so it doesn't belong in this tally, even though it's still real money leaving your account.
The whole formula, in one line
Assets − Liabilities = Net Worth. If your home has a large mortgage against it, this number can come out negative early on — that's normal, not a crisis. The point of this step isn't the number itself. It's knowing it, instead of guessing at it.
Doing this once, by hand, is a good exercise. Doing it every month by hand is how most people quietly stop doing it by March. If you'd rather have this number update itself as you go, that's the whole idea behind a proper budgeting app instead of a spreadsheet you re-open twice a year.
Step 4: Pick a budgeting method you'll actually use
There are two methods almost everyone lands on eventually. Neither is objectively "better" — the one that wins is the one you're still using in six months.
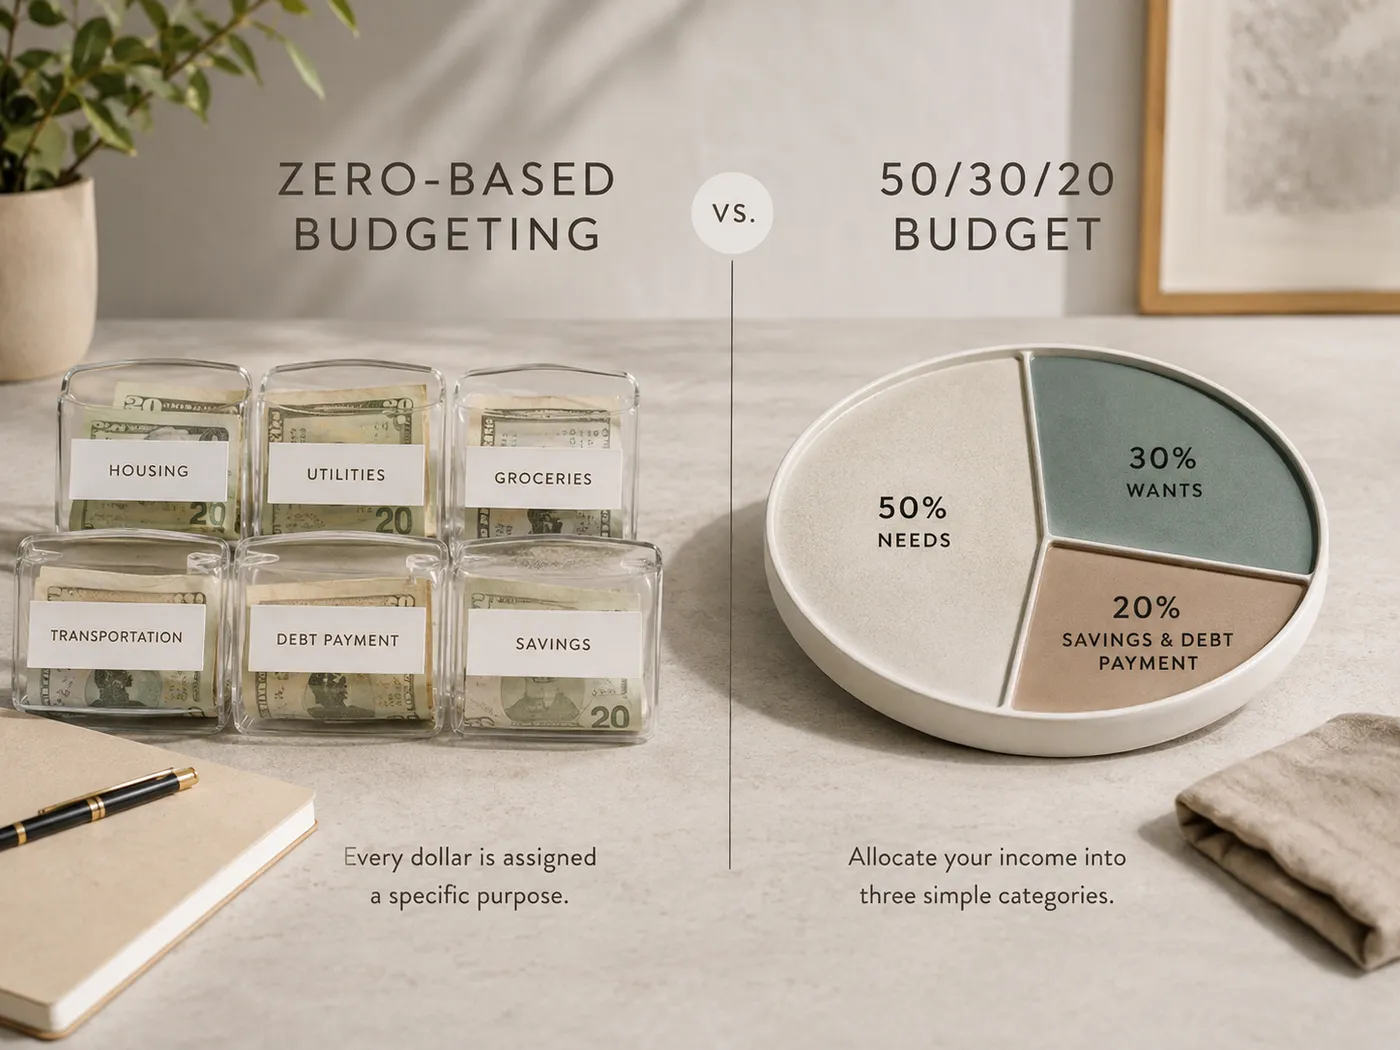
Method 1: Zero-based budgeting (give every dollar a job)
Every month, every dollar of income gets assigned somewhere until you hit zero left unassigned. Nothing sits around without a job. To run it: write down your monthly income, write down every expense (needs first, then wants), don't forget seasonal costs like annual property tax or registration, subtract expenses from income until it lands on zero, then track spending daily enough to catch drift.
The catch: it demands monthly attention. Every month is a fresh plan built from that month's numbers, which is exactly why so many people start strong in January and quietly abandon it by March — not because the method is wrong, but because doing it by hand, every month, forever, is a lot to ask of anyone.
Give each part of your spending a place
TidyEnvelopes helps you organize spending and savings into digital envelopes. Record purchases, check recorded balances, and plan how to fund your envelopes on payday. You stay in charge of entering transactions and making any actual bank transfers.
List price $49 $27 one-time.
Method 2: The 50/30/20 rule
Simpler on paper: 50% of your income covers needs, 20% goes to savings and debt paydown, and 30% is yours to spend on wants, guilt-free. If your "needs" genuinely run over 50% — an expensive car payment, say — you borrow room from the "wants" slice rather than pretending the number isn't real.
The appeal is that once it's set up, you're not re-deciding your whole budget every month. You know your number for wants, the rest runs on autopilot, and you check in periodically instead of constantly.
Bring your household budget into one view
TidyBudget brings budget tracking, bills, accounts, debt tools, and sinking funds into one browser-based app. Use household and personal views to organize your own numbers and keep future expenses in the plan.
List price $69 $47 one-time.
Whichever you pick, the method itself matters less than you'd think. What actually matters is whether it survives contact with a real month — the one with the car repair and the birthday party and the "we're out of everything" grocery run.
Step 5: Actually track it
This is the step almost everyone skips, and it's the one that decides whether the first four steps meant anything. A budget you never check is just a document. Here's what tracking actually looks like, every month and every year:
- Check every statement, every account. Mistakes happen. So does theft. Five minutes a month catches both.
- Track the expenses that don't feel like "real" spending. The coffee, the gas-station candy bar, the subscription you forgot existed.
- Let technology do the boring part. Notifications, auto-categorizing, balance tracking — you shouldn't be doing arithmetic by hand in 2026.
- Note what's improving and what isn't. Debt trending down? Investments performing as expected? Write it down, don't just vibe-check it.
- Check the year, not just the month. A monthly view hides slow trends that a yearly view makes obvious.
- Pull your credit report, yearly, free. All three bureaus. It's your legal right and it takes ten minutes.
- Reassess your goals, yearly. What mattered last January might not matter this one.
- Be ready to change the plan. A lost job means a temporary emergency budget, not a scrapped plan — the whole point of the emergency fund from Step 1 is that this doesn't have to turn into debt.
Keep due dates, payments, and balances together
TidyExpenses brings recurring bills, partial payments, and remaining balances into one place. Review what needs attention, record what you paid, and see bills across the calendar. It tracks your entries; it does not make or verify bank payments.
List price $49 $27 one-time.
The tools everyone recommends
Your bank probably already has decent budgeting tools built in — check there first, it's free and it's already connected. Beyond that, a few names come up constantly in every "best budgeting tools" list, so here's the honest state of them:
- Mint — for years, the default answer. Intuit shut it down in 2024 and pushed everyone toward Credit Karma instead, so if you see it recommended somewhere, it's stale advice.
- YNAB (You Need a Budget) — still around, still genuinely good, built around the same zero-based philosophy as Step 4. It's a subscription (check their site for current pricing), and it connects to your bank accounts directly.
- Investor.gov — a real, free U.S. government site with solid calculators (compound interest, retirement estimates) and a genuinely good youth-education section. If you're outside the US, look for your own country's equivalent — the tax and retirement specifics won't transfer.
- Credit Karma — free credit monitoring, now also where former Mint users landed. Worth ignoring the credit-card ads it shows you.
Or skip the subscription entirely
Every tool above that actually works well also wants your bank login and a recurring charge. That's a fair trade for some people. If it's not for you, that's the whole reason TidyCents exists: one-time payment, nothing connected to your bank, and your numbers never leave your device. See the free tools and the paid ones →
For checklists and templates specifically, sites like Smartsheet and Templatelab still offer free financial-planning templates for Excel and Word — useful if you want to build your own system from scratch rather than use an app at all. And for organizing the paperwork side of things (insurance, accounts, estate documents in one place), a service like Everplans is worth a look — check their current pricing before signing up, as it's changed over the years.
When to actually hire someone
You can do everything in this guide yourself. Plenty of people do. But there's a real category of situations where a professional earns their fee fast, mostly because you don't know what you don't know — you can't ask the right question if you've never heard of the concept behind it.
- Personal financial planner — works with you long-term across your whole financial life. Some charge commission, some an hourly or flat fee — ask upfront.
- Financial advisor — more short-term and transactional, often for a specific investment or account decision. The line between "advisor" and "planner" has blurred, so ask what they actually do.
- Accountant / CPA — not just for business owners. Real tax-planning help, not just tax filing, if they hold a CPA.
- Insurance agent — helps you get the right coverage instead of the most coverage.
- Attorney — wills, living trusts, property, and (if needed) bankruptcy reorganization. Find one who specializes in what you actually need.
- Investment advisor — for when you have money to invest and no clear idea how.
- Debt counselor — a last resort, not a first move — there are usually faster paths out of debt trouble than a formal counseling program.
- Money coach — think Dave Ramsey or Suze Orman: less technical execution, more education and accountability.
Whoever you hire, interview more than one, check their actual credentials, and treat "too good to be true" as a hard stop. Scammers are very good at sounding like the professional you were looking for.
Build your monthly plan through conversation
Budget Plan Agent helps organize your income, bills, spending, savings goals, and irregular costs into a monthly plan, a weekly spending number, and a 30-day action plan. It works with supported versions of ChatGPT and Claude; platform access is separate. It is educational budgeting support, not a replacement for professional advice.
List price $39 $17 one-time.
Why most financial plans fail
Not because people are bad with money. Usually it's one of these, quietly, for months:
- You don't know what you don't know. Sometimes the situation is complicated enough that only an expert knows the right question to ask.
- You stop monitoring it. Kids, work, life — time gets away from everyone. The plan doesn't fail loudly; it just stops being looked at.
- You keep putting it off. "Later" always feels available until the years that were supposed to hold it are gone.
- You're too restrictive. A plan that bans your one daily coffee doesn't survive contact with real life. Be honest about where you actually have discipline.
- You're trying to plan around too little income. If the basics aren't covered, the plan needs to be "make more money" before it can be anything else.
- You save too much and live too little. Rare, but real — some people over-correct so hard they stop enjoying money that's already theirs.
- You spend too much for your income. The uncomfortable but necessary question: is this rent actually realistic at what you make?
- You ignore the long term. Compounding needs time more than it needs a big number to start with.
- You ignore the short term. You're allowed to enjoy your life now, not just plan for a future version of it.
- Your goals aren't SMART. Specific, measurable, attainable, realistic, time-bound. "Save more" isn't a goal. "Save $200/month starting next payday" is.
- You trusted the wrong person. A guaranteed high return is the single biggest tell of a scam. Verify credentials — don't take a friend's or a relative's word for it. Scammers are good at recruiting whole families.
The throughline in almost all of these: the plan has to match your actual personality and your actual numbers, not someone else's idea of what a "good" plan looks like. What you want is what matters here — not what a finance influencer wants for their own life.
Okay. Where do you actually start?
Right now, in whatever order makes sense to you:
- Figure out where you actually stand. What's coming in, what's going out, what could realistically change on either side.
- Know where you want to go. What does the day you retire — or the day you're debt-free, or the day you buy the house — actually look like?
- Find the right help. Not necessarily a $200/hour planner on day one — sometimes it's a good tool, sometimes it's a guided conversation, sometimes it genuinely is a professional.
- Actually do it. Time moves faster than it feels like it's moving. The plan you start imperfectly this month beats the perfect plan you're still designing in six.
That's really the whole thing: know where you are, know where you're headed, check in on it periodically, and adjust when life doesn't cooperate — because it won't, at least once. A plan doesn't have to be perfect to work. It just has to exist, and get looked at.
If even step one feels like a lot right now
Start smaller than a full financial plan. The Money Leak Score takes about two minutes, asks a handful of plain questions, and shows you the one leak worth fixing first — no bank login, nothing saved, completely free.